Sea Breeze Mortgages and Payment Plans: Ready or Off-Plan?
The ways to pay for a Sea Breeze home, and how to choose between ready and off-plan, explained plainly and without the campaign hype.
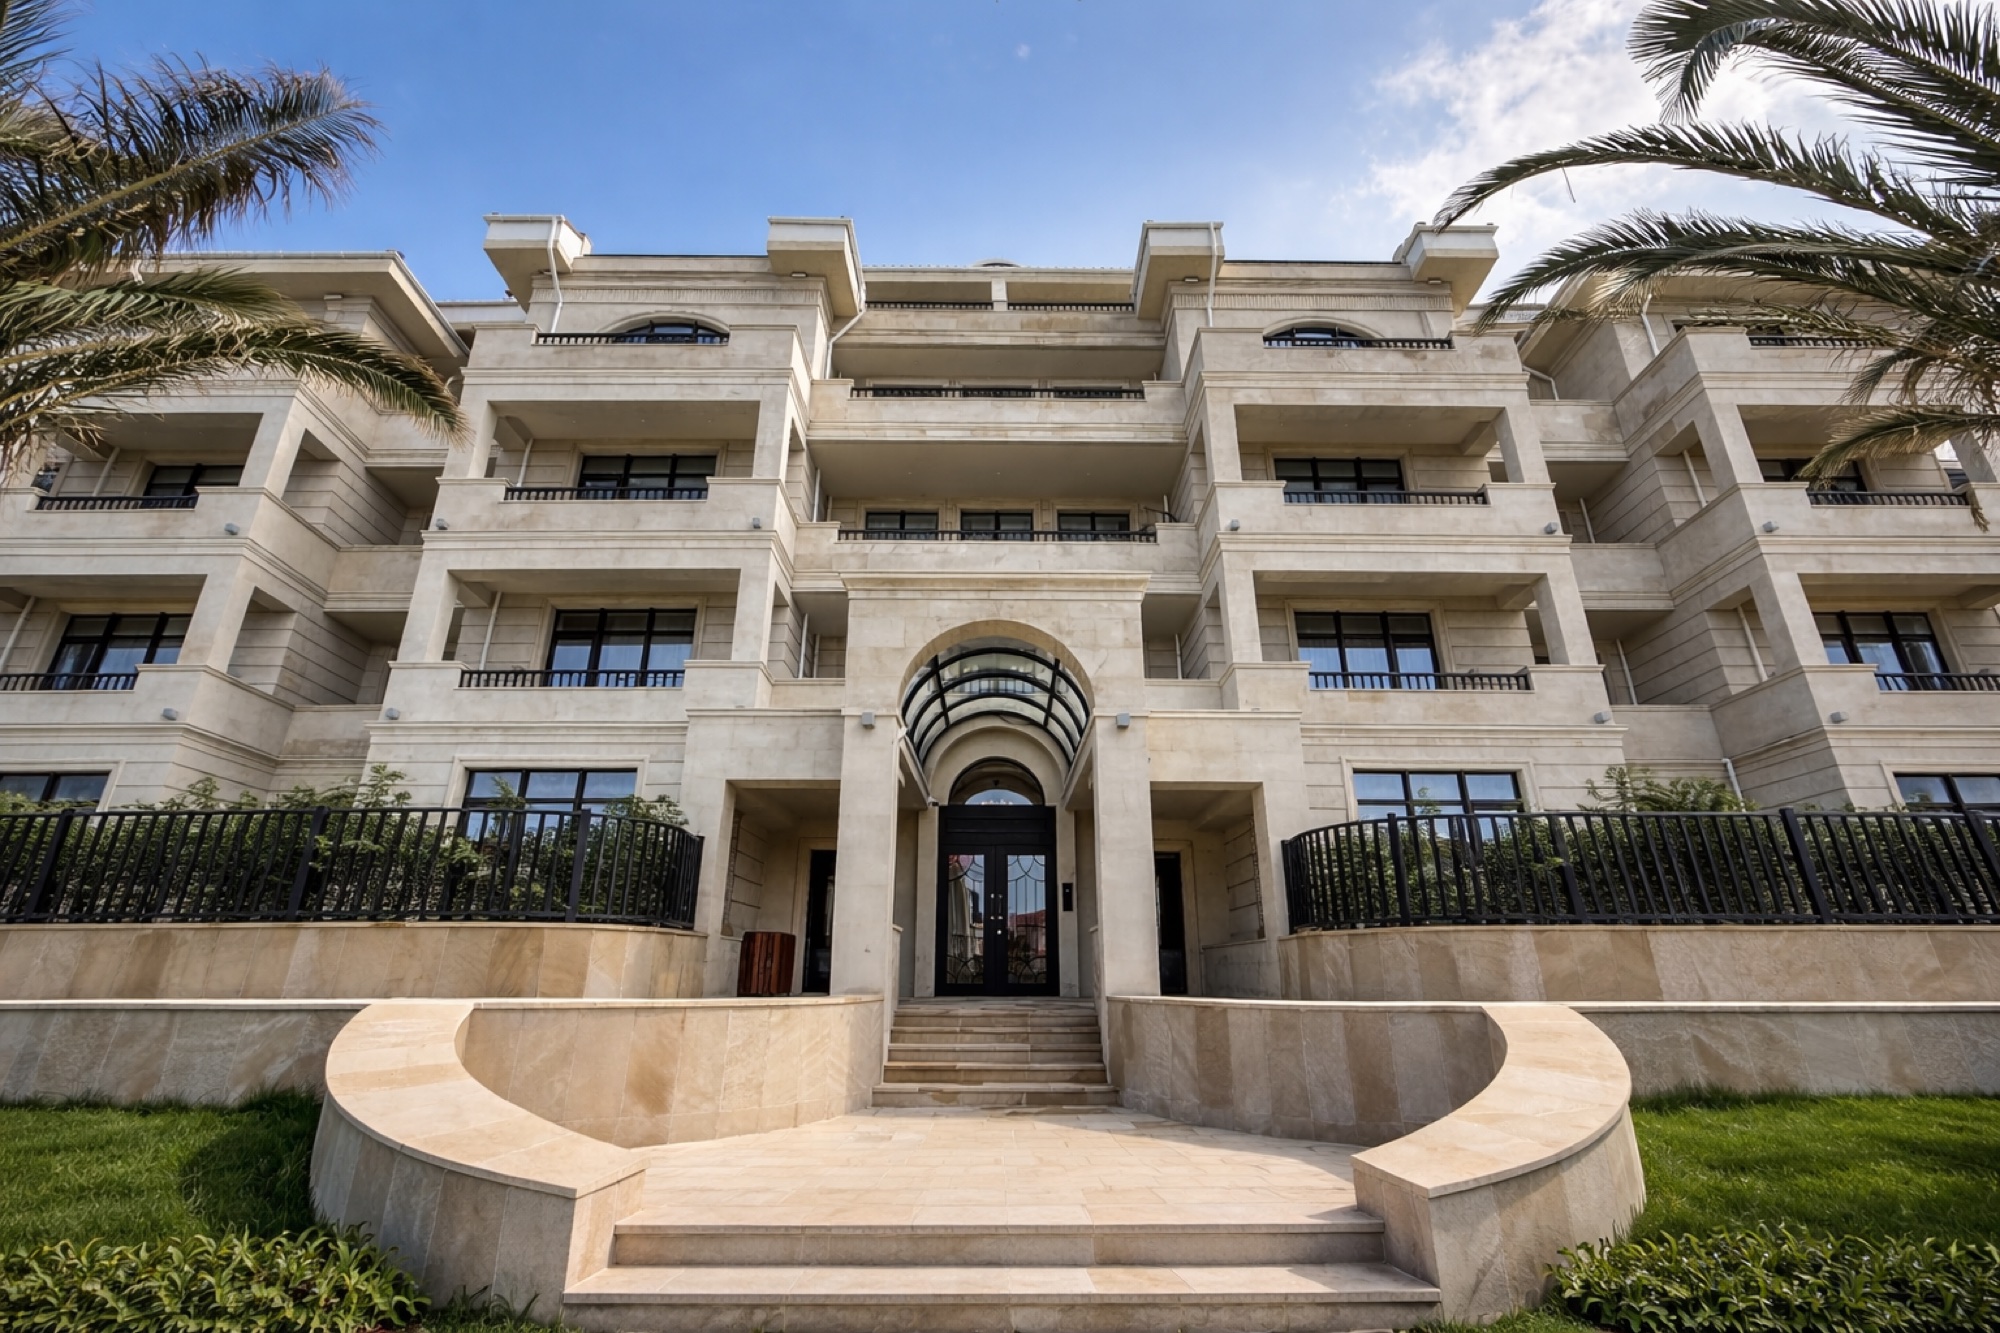
You can buy a home at Sea Breeze with cash, a developer instalment plan, a bank mortgage, a trade-in, or by taking over an existing mortgage, and the terms depend on the project and the current campaign. A ready home means you can move in, let it and hold a registry extract straight away. An off-plan unit usually comes with a more flexible payment plan, but you wait for the keys. Sea Breeze Properties helps buyers at Sea Breeze, Nardaran, Baku, compare both routes and build a payment structure around their income and plans.
Campaign terms change fast. The examples here show the general picture; ask us for today's down payment, rate and term.
Ways to pay
Cash
The simplest and fastest route. On the resale market, cash buyers have more room to negotiate. For example, the 56.7 m² apartment in Sky Park in our catalogue has been reduced from $119,070 to $83,300 for a cash purchase.
Developer instalment plans
At different times the developer has offered instalment plans on new projects, some of them interest-free. One example is a 36-month plan with a down payment starting at 50% of the price. The down payment and term depend on the project. An instalment plan needs no bank checks, but always confirm in the contract when ownership will pass to you.
Bank mortgages
The developer runs mortgage campaigns with partner banks. For example, one summer campaign offered 10-year mortgages with a 10% down payment on selected projects. With ABB it has also launched a "hybrid mortgage", where part of the price is financed by a bank loan and the rest by an interest-free developer instalment plan.
Subsidised state mortgages have their own criteria and are not open to every buyer or every property; the bank checks eligibility. For foreigners, bank mortgages are limited. More in Property for foreigners and residency.
Taking over a mortgage
Sometimes a seller sells with a mortgage still running. The buyer pays an upfront amount and, with the bank's consent, takes over the remaining monthly payments. Our catalogue has an example: a 46.1 m² pool-view apartment in Lighthouse 2, with 50,000 AZN down and then 1,486 AZN a month. With this structure we always check the outstanding balance, the rate and the bank's terms before you commit.
Trade-in
The developer has offered trade-in on some projects, including Polo Residences and Park Residences 2. Your existing property is valued and counted towards the new home. Sea Breeze Properties also offers trade-in to its clients.
Ready homes: pros and cons
Pros:
- you see exactly what you buy: the view, the light, the neighbours;
- you can move in or let it straight away;
- you receive the registry extract, which can support a residence-permit application;
- there is no construction-delay risk.
Cons: you usually pay in cash or with a bank mortgage, and there are fewer instalment options.
Off-plan: pros and risks
Pros:
- flexible instalment plans;
- an early choice of floor and layout;
- the price may rise before handover (not guaranteed).
Risks:
- the handover date can slip;
- the finished product can differ from the renderings;
- there is no rental income before handover;
- there is no basis for a residence permit until the unit is registered.
To reduce the risk, make sure the contract states the exact handover date, the compensation for delays and the condition the unit will be delivered in. Check the payment schedule against the real progress of construction.
Renovated or shell?
A renovated (turnkey) home saves time and can earn from day one, like the renovated 81 m² apartment in Lighthouse 4. A shell unit gives you more freedom, like the 75 m² two-room apartment in Polo Residences. But you need to budget the renovation and allow several months for it.
How to compare payment options
A small monthly payment does not make a structure cheap. When comparing options, look at:
- The total cost: every payment added up, including the down payment, monthly payments, interest, insurance and fees.
- The contract currency: whether the price is fixed in AZN or USD, and which currency you earn in.
- Early repayment: whether you can clear the balance early, and whether there is a penalty.
- Late-payment terms: what happens if a payment is late.
- When ownership passes: the date the home is registered in your name.
What Sea Breeze Properties does at this stage
We gather the developer's and banks' current terms, model the total cost across two or three realistic scenarios, and check contract clauses such as the handover date, penalties and the transfer of ownership. We also coordinate with the bank, the notary and the seller.
Five questions to decide
- When do you need the keys?
- How much can you pay each month, and is your income stable?
- Do you plan to apply for residency?
- Will you let the home out?
- Do you have the time and budget to renovate?
Once you have answered these, the choice usually becomes clear. For every step of the purchase, see How to buy at Sea Breeze.
Let's go through the current campaigns and work out the right payment structure for you: contact us.
Questions and answers
Can I buy at Sea Breeze with a mortgage?
Yes. The developer runs mortgage campaigns with partner banks and launched a "hybrid mortgage" with ABB. The down payment, rate and term vary by campaign, so ask Sea Breeze Properties for the current terms.
Does Sea Breeze offer payment plans?
Yes. The developer offers instalment plans on new projects, some of them interest-free, with no bank checks required. The down payment and term depend on the project.
What does taking over a mortgage mean?
You buy a home that still carries the seller's mortgage: you pay an upfront amount and, with the bank's consent, continue the monthly payments. The outstanding balance and the bank's terms must be checked before the deal.
Is it better to buy ready or off-plan?
If you need to move in, let the home or apply for residency, a ready home is the better fit. If you want a flexible payment plan and can wait, off-plan is worth considering, as long as you allow for the risk of delays.
Thinking about buying at Sea Breeze?
Talk to a specialist — we reply within 24 hours.